Skip to content
AICPA-CIMA
  • AICPA & CIMA:
  • Home
  • Engage 365 Communities
  • CPE & Learning
  • My Account
Journal of Accountancy
  • TECH & AI
    • All articles
    • Artificial Intelligence (AI)
    • Microsoft Excel
    • Information Security & Privacy

    Latest Stories

    • Why AI needs to show its work
    • How firms make AI adoption work for them
    • Sales tax doesn’t have to be this hard

  • TAX
    • All articles
    • Corporations
    • Employee benefits
    • Individuals
    • IRS procedure

    Latest Stories

    • IRS expands Tax Pro Account to allow payments on behalf of business clients
    • IRS announces inflation adjustments for tax year 2027
    • Why AI needs to show its work
  • PFP
  • PRACTICE MANAGEMENT
    • All articles
    • Diversity, equity & inclusion
    • Human capital
    • Firm operations
    • Practice growth & client service

    Latest Stories

    • IRS expands Tax Pro Account to allow payments on behalf of business clients
    • U.S. employee engagement falls below 30% for first time in 15 years
    • IRS announces inflation adjustments for tax year 2027
  • FINANCIAL REPORTING
    • All articles
    • FASB reporting
    • IFRS
    • Private company reporting
    • SEC compliance and reporting

    Latest Stories

    • SEC proposal aims to clarify securities rules for crypto assets
    • SEC eyes e-delivery as the default over paper
    • SEC shares 3 goals in proposed 2026–2030 strategic plan
  • AUDIT
    • All articles
    • Attestation
    • Audit
    • Compilation and review
    • Peer review
    • Quality Management

    Latest Stories

    • AI raises the stakes for auditor judgment
    • How CPAs are putting AI to work in audits
    • Center for Audit Quality taps Dave Sullivan as CEO
  • MANAGEMENT ACCOUNTING
    • All articles
    • Business planning
    • Human resources
    • Risk management
    • Strategy

    Latest Stories

    • U.S. employee engagement falls below 30% for first time in 15 years
    • Risk response often doesn’t match the threat or the opportunity
    • Confidence in U.S. economy rises despite inflation concerns
  • Home
  • News
  • Magazine
  • Podcast
  • Topics
Advertisement
  1. newsletter
  2. Cpa Insider
CPA INSIDER

High-deductible Medigap plan makes sense for some

A Medicare beneficiary at the ‘break-even’ age may benefit from switching to a high-deductible policy.

By James Sullivan, CPA/PFS
March 19, 2018

Please note: This item is from our archives and was published in 2018. It is provided for historical reference. The content may be out of date and links may no longer function.

Related

March 1, 2018

How 65 became the default retirement age

March 1, 2018

Clients are living longer: How will your practice adapt?

February 1, 2018

Help clients balance retirement and education planning

TOPICS

  • Personal Financial Planning
    • Retirement Planning
    • Practice Management

The Annual Enrollment Period isn’t the only time Medicare beneficiaries can make changes to their coverage to better meet changing financial circumstances. Participants in traditional Medicare can make changes to their Medicare Supplement (or Medigap) coverage any time during the year for any reason. One such change you may recommend to your clients is moving from traditional Medigap Plan F (Medigap F) to a high-deductible Plan F (Medigap High-F).

Medigap F provides the most comprehensive coverage of the current Medigap plans offered. With Medigap F there are no annual deductibles and no out-of-pocket costs for procedures covered by Medicare. Because it offers comprehensive coverage, its monthly premium is the highest when compared to the other Medicare Supplement plans. Despite its high premium, it is the most popular Medigap plan.

Medigap High-F has been available for several years. It provides the same coverage as Medigap F but has much lower premiums. However, it does have an annual deductible of $2,240 in 2018.

How does it work? Medicare Parts A and B continue to pay covered costs first. For example, if you go to your primary care physician and the Medicare-approved cost of the visit is $100, Medicare Part B will pay 80% of the cost or $80. (See table below.) Under Medigap F, the policy will pay the balance owed of $20 leaving the client with no out-of-pocket (OOP) costs. Under the Medigap High-F, if the client has not yet reached the annual deductible of $2,240, he or she would pay the $20 OOP cost. The Medicare beneficiary will continue to pay the amount that Medigap F would have paid for medical services until his or her total OOP costs reach $2,240.
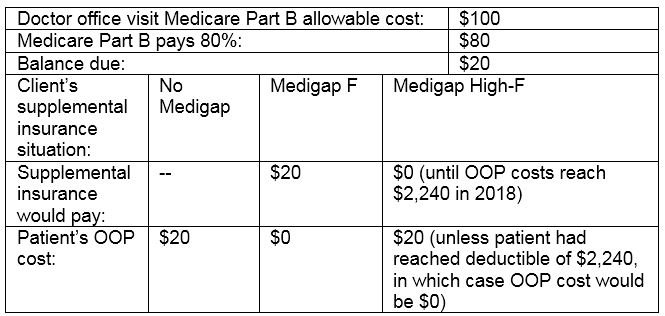
Medigap F comparison


Many Medigap High-F policyholders are unlikely to reach the annual deductible of $2,240. But the risk of paying that much OOP costs still exists, especially if a policyholder is in poor health.

When Medigap High-F plans may be a good choice

There is one way for a client to move to Medigap High-F without being “at risk”: by switching to Medigap High-F once he or she has reached the “break-even” age.

At certain ages a client’s annual savings in Medigap High-F premiums compared to Medigap F premiums will exceed the annual deductible. This is what is referred to as the “break-even” age. In the example below, age 81 is used to illustrate the point, but the break-even point can be lower for some beneficiaries, depending on Medigap prices and the state they live in.

Advertisement

For an 81-year-old woman, the annual premium cost of Medigap F from a large, financially strong insurance company in a Midwestern state is $3,084. The annual premium cost of the same company’s Medigap High-F is $847.08 for a total cost savings of $2,236.92. The annual deductible in 2018 is $2,240, or within a few dollars of the break-even point. Therefore, it may make sense for this client to switch to a Medigap High-F plan, especially if she is in good health and anticipates spending less than the deductible in health care costs.

The savings increase after age 81. At age 85 the difference between the Medigap F premium ($3,840) and the Medigap High-F premium ($1,224) is $2,616, greater than the annual deductible.
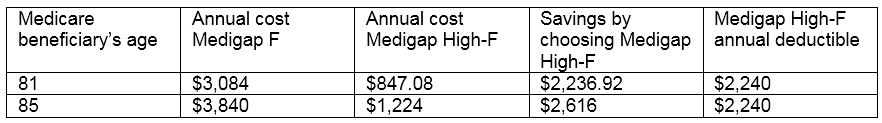
Savings comparison


Even if a client is younger than the break-even age, a Medigap High-F plan may still make sense. It does mean that the adviser should perform aareful analysis of the potential savings from selecting a Medigap High-F plan and determine the amount the client is “at risk.” For example, a 72-year-old female client may purchase a Medigap F for $2,808 per year. A Medigap High-F plan from the same provider in her state would cost $864. The $1,944 in premium savings is less than the annual deductible of $2,240. But if your client considers herself in good health, she may decide that the amount she would save by choosing a Medigap High-F plan is worth chancing the “at risk” amount of $2,240 minus $864, or $1,376.

Finances aren’t the only factor to consider during Medicare planning

In other cases, clients may want to switch to a Medigap High-F plan for reasons other than money.

For example, one client’s 96-year-old mother participated in a Medicare Advantage (MA) plan with a monthly premium of $25 ($300 per year). The MA plan included prescription drug coverage. MA plans include various co-payments and co-insurance the beneficiary must pay out-of-pocket. MA plans must have an overall annual OOP cost limit, but these limits are usually very high at $3,600 or more.

However, the mother was homebound and depended on her daughter to take her to doctor’s appointments. The MA plan had network restrictions limiting the health care providers that beneficiaries could use. Its service area was limited to the county in which the mother lived so seeing a doctor nearer to her daughter’s home in another county was not possible. By moving from her MA plan (during the Annual Enrollment Period) to traditional Medicare plus a Medigap High-F, the mother could select a new doctor very close to her daughter’s home.

In this case, cost was important, but a secondary consideration. However, the client’s mother still saved money by choosing a Medigap High-F over a Medigap F. A Medigap F would have cost her $4,164 per year. The Medigap High-F would cost $1,320. The savings can be calculated as follows:

Advertisement

Annual premium cost of traditional Plan F  $4,164

Less: Annual premium cost of Medigap High-F  ($1,320)

Plus: Savings from dropping the MA plan*  $300

Total savings before the annual deductible  $3,144

*Premium of $25 monthly or $300 per year; does not include the MA plan co-payments and co-insurance amounts.

With the annual high deductible in 2018 of $2,240, the client’s mother was not at risk given the overall savings in monthly premium costs. The OOP costs of her Medicare Part D standalone plan (including the annual deductible, co-insurance, and co-payments) given her current prescription drugs were approximately the same as prescription drug coverage under the MA plan. All else being equal, the move to traditional Medicare with a Medigap High-F and a standalone Part D plan provided a net savings.

As these examples illustrate, proactive Medicare planning can often result in better coverage and cost savings as your client’s health and financial circumstances change.

Advertisement

James Sullivan, CPA/PFS, is a financial planner in Wheaton, Ill. He specializes in working with clients, and the families of clients, suffering from chronic illness. To comment on this article or to suggest an idea for another article, contact Courtney Vien, a JofA senior editor, at Courtney.Vien@aicpa-cima.com.


Advertisement

latest news

November 6, 2026

IRS expands Tax Pro Account to allow payments on behalf of business clients

November 6, 2026

U.S. employee engagement falls below 30% for first time in 15 years

November 5, 2026

IRS announces inflation adjustments for tax year 2027

November 4, 2026

FASB proposes simpler approach for equity-linked contracts

November 3, 2026

AICPA proposes ethics guidance for alternative practice structures

Advertisement

Most Read

AI and the audit: AICPA publishes practice aid to assist auditors
Social Security wage base and COLA announced for 2027
AICPA partners on new offering that assures AI systems and agents
Using an Excel agent to clean, validate, and reconcile data
New checklist helps CPAs manage AI cyber risks
Advertisement

Podcast

November 5, 2026

Building a career defined by impact, not accolades or titles

October 29, 2026

Turning risk intelligence into strategic advantage

October 22, 2026

Why finance leaders don’t need to have all the answers

Features

AI raises the stakes for auditor judgment

AI raises the stakes for auditor judgment

How CPAs are putting AI to work in audits

How CPAs are putting AI to work in audits

How to craft the CPA career you want

How to craft the CPA career you want

Not-for-profit pay faces broader tax risk

Not-for-profit pay faces broader tax risk

Why AI needs to show its work
Accordance

Why AI needs to show its work

How firms make AI adoption work for them

How firms make AI adoption work for them

Sales tax doesn’t have to be this hard

Sales tax doesn’t have to be this hard

SPONSORED REPORT

Get your clients ready for tax season

Help clients avoid surprises with year-end planning strategies for managing taxable income, maximizing deductions, and adjusting to OBBBA changes affecting individuals and businesses.

From The Tax Adviser

October 31, 2026

AI risks to the Sec. 7525 practitioner privilege

September 30, 2026

Navigating the QSBS rules in pass-through structures

September 30, 2026

Sec. 338(h)(10) elections in business acquisitions

August 31, 2026

2026 tax software survey

MAGAZINE

November 2026

November 2026

November 2026
October 2026

October 2026

October 2026
September 2026

September 2026

September 2026
August 2026

August 2026

August 2026
July 2026

July 2026

July 2026
June 2026

June 2026

June 2026
May 2026

May 2026

May 2026
April 2026

April 2026

April 2026
March 2026

March 2026

March 2026
February 2026

February 2026

February 2026
January 2026

January 2026

January 2026
December 2025

December 2025

December 2025
view all

View All

http://JofA_Default_Mag_cover_small_official_blue

PUSH NOTIFICATIONS

Learn about important news

This quick guide walks you through the process of enabling and troubleshooting push notifications from the JofA on your computer or phone.

CPA LETTER DAILY EMAIL

CPA Letter Logo

Subscribe to the daily CPA Letter

Stay on top of the biggest news affecting the profession every business day. Follow this link to your marketing preferences on aicpa-cima.com to subscribe. If you don't already have an aicpa-cima.com account, create one for free and then navigate to your marketing preferences.

Connect

  • X Logo JofA on X
  • facebook JofA on Facebook

HOME

  • News
  • Monthly issues
  • Podcast
  • A&A Focus
  • PFP Digest
  • Academic Update
  • Topics
  • RSS feed rss feed
  • Site map

ABOUT

  • Contact us
  • Advertise
  • Submit an article
  • Editorial calendar
  • Privacy policy
  • Terms & conditions

SUBSCRIBE

  • Academic Update
  • CPE Express

AICPA & CIMA SITES

  • AICPA-CIMA.com
  • Global Engagement Center
  • Financial Management (FM)
  • The Tax Adviser
  • AICPA Insights
  • Global Career Hub
AICPA & CIMA

© 2026 Association of International Certified Professional Accountants. All rights reserved.

Reliable. Resourceful. Respected.